Finland's Economic Update July 2018  In the first quarter of 2018, the economy maintained its growth momentum from Q4 2017...


Finland's Economic Update July 2018 

In the first quarter of 2018, the economy maintained its growth momentum from Q4 2017, with quarter-on-quarter growth accelerating to an over seven-year high. This was due to fixed investment surging on the back of higher private sector investment. Moreover, government consumption increased in Q1, contrasting the fall in Q4. However, although unemployment decreased, and consumer confidence hit record highs, private consumption growth decelerated in Q1 from Q4. This may have been due to high household debt levels weighing on consumer spending. The external sector, for its part, detracted from growth. Meanwhile, the economy had a weak start to Q2. In April, economic activity expanded year-on-year at the slowest pace since August 2016. The current account balance also logged a deficit for the second consecutive month in April.  An expansion in private consumption should support economic growth in 2018 as unemployment dips from 2017. Moreover, accommodative monetary policy and high business confidence are seen supporting an expansion in fixed investment. However, the government’s ongoing fiscal consolidation will likely constrain government consumption growth. FocusEconomics panelists expect GDP growth of 2.7% in 2018, which is up 0.2 percentage points from last month’s forecast, and 2.2% in 2019. Harmonized inflation accelerated to 1.1% in May from 0.8% in April. Our panelists see harmonized inflation averaging 1.1% in 2018 and 1.3% in 2019.


REAL SECTOR | Economic activity growth takes a breather in April 
Economic activity grew a working-day adjusted 1.8% in April compared to the same month last year, down from a significantly revised 4.0% in March (previously reported: +3.1% year-on-year) and the lowest growth rate since August 2016. This is according to the latest monthly Trend Indicator of Output released by Statistics Finland. The weaker result in April came as services production, the largest output category in Finland, registered a slower pace of growth of 2.0%, down from 2.9% in March. Moreover, secondary production, which comprises the manufacturing and construction sectors, grew 1.3% in April, down substantially from 6.3% in March. Meanwhile, primary production was solid in April, growing 8.1% (March: +2.6% yoy). A month-on-month comparison shows that economic activity on a seasonally adjusted basis contracted 0.9% in April, in contrast to the revised 0.9% expansion in March (previously reported: +0.6% month-on-month). Average year-on-year growth in economic activity ticked down to 2.9% in April from 3.0% in March.


Comprehensive data confirmed that the Eurozone economy lost steam in Q1, growing at the weakest pace since Q2 2016. The external...


Comprehensive data confirmed that the Eurozone economy lost steam in Q1, growing at the weakest pace since Q2 2016. The external sector was primarily behind the slowdown, with a strong euro and slowing global recovery fueling a decline in overseas sales. Data for Q2 suggests that momentum has regained some lost ground, although growth is likely still below last year’s highs. The unemployment rate hit a new multi-year low in April, and strong services sector growth pushed the composite PMI up in June. That said, data for the manufacturing sector has been weak, with industrial production contracting in May and the manufacturing PMI falling to an 18-month low the month after. Moreover, the outlook for the sector has turned gloomier in recent weeks. On 22 June, U.S. President Donald Trump threatened to slap a 20% tariff on all European Union manufactured automobiles if retaliatory tariffs on U.S. goods enacted by the EU were not lifted. While the U.S.’s initial tariffs on steel and aluminum are expected to have a relatively small economic effect, the automobile industry is a much larger sector and tariffs could dampen manufacturing activity. FocusEconomics panelists cut 0.1 percentage points off the Eurozone’s growth forecast for 2018 this month and now see GDP growing 2.2% in 2018. A weak first quarter and rising political risks are dampening the outlook, although growth is expected to remain healthy overall thanks to a solid domestic economy. In 2019, the economy is seen expanding 1.9%. Harmonized inflation jumped from 1.3% in April to 1.9% in May amid higher energy costs. As a result, inflation is around the ECB’s target of close to 2.0%. Our panel sees inflation averaging 1.6% in both 2018 and 2019.


Amid a healthy recovery and rising price pressures, the ECB announced it was winding down its massive bond buying program on 14 June, with purchases set to end completely after December. However, the Bank still struck an accommodative tone, stating that it plans to hold the refinancing rate at a record-low 0.00% until the end of next summer. The next meeting is set for 26 July. The Consensus Forecast is that the refinancing rate will end 2018 at 0.00% and 2019 at 0.30%.


The euro continued to flounder against the U.S. dollar in June, remaining at some of the lowest values seen in 2018. On 22 June, the euro bought 1.16 USD, weakening 1.2% from the same day last month. Our panel sees the currency ending 2018 at 1.21 USD per EUR and 2019 at 1.26 USD per EUR.


Italy Update Following three months of political deadlock and two unsuccessful attempts to form a government, on 6 June the...


Italy Update

Following three months of political deadlock and two unsuccessful attempts to form a government, on 6 June the Italian Parliament signed off on a government formed by the right-wing League party and the leftist populist Five Star Movement. As the two parties have different ideologies and the coalition agreement is the result of complicated negotiations, governing will not be smooth sailing. The deadlock has been resolved at a time when the recovery seems to have lost some steam. Recent GDP data shows that growth was broadly stable in Q1, but the economy shows some signs of having slowed in Q2, partly affected by subdued growth in the whole eurozone. In April, the industrial sector weakened considerably, and retail sales contracted sharply amid falling consumer confidence. However, NPLs declined further, confirming that the banking sector has indeed turned a corner, and the construction sector rebounded significantly. That said, survey-based indicators deteriorated further in May, a consequence of both weak external demand and the difficult political situation. • Going forward, Italy will navigate in uncharted political territory. Political uncertainty, together with possible financial turbulence, represents the main downside risk to growth, especially in light of the fragility of Italy’s public finances. That said, further improvements in the banking sector should help strengthen business credit and investment, while moderate inflation and employment gains should support consumer spending. FocusEconomics panelists project growth of 1.3% in 2018, down 0.1 percentage points from last month’s forecast, and 1.2% in 2019. • Harmonized inflation rose to 1.0% in May from 0.6% in April. Moderate domestic pressures will restrain inflation, although higher prices for fuels will act in the opposite direction. Our panelists expect inflation to average 1.2% in 2018 and 1.3% in 2019.


Political turmoil

Following months of deadlock, Italy forms a new government but still faces many unknowns Three months after the elections and following two failed attempts to form a government, on 6 June the Italian parliament finally ended the political impasse and voted for a government formed by the populist Five Star Movement (M5S) and right-wing League party. The deadlock was broken when the League accepted to replace their pick for Minister of Finance, Paolo Savona, who was vetoed by the president, with Giovanni Tria, a university professor with a less Eurosceptic profile. Financial markets reacted nervously, sending the 10-year bond yield above 3.0% in the days following the arrival of the new government, although yields declined thereafter. The new coalition’s proposed economic program, based on an agreement reached in mid-May following complex negotiations, is protectionist and fiscally expansionary, including both tax cuts and higher spending. It has, however, vague details on how to provide adequate financing. The proposed measures, combined with Italy’s colossal public debt and already sizeable fiscal deficit, could cause severe financial distress, especially at a time when the European Central Bank is preparing to reduce its monetary stimulus. However, a large degree of uncertainty exists over the extent to which the coalition will be able to enact its program, due to the ideological and territorial differences between the two parties and their electorates. The introduction of a proposed two-tier flat tax (at 15% and 20%) on personal and corporate income could help reduce the country’s heavy tax burden, improve competitiveness and boost both consumer and corporate spending; however, it could also jeopardize government revenues. The proposed guaranteed income, which would provide a minimum income of EUR 780 per month for a single household for a maximum of two years, along with changes to how the retirement age is determined, could increase already bulky public spending and dent labor market participation, which is already at one of the lowest rates in the European Union. In addition, a proposed new hourly minimum wage could raise labor costs for firms, hitting employment. Relations with European institutions will, furthermore, likely become strained under the new government. The coalition program commits the future government to promoting an amendment to existing European treaties that would devolve to member states some of the competences currently held by European institutions. Moreover, it questions EU rules on the fiscal deficit and proposes to exclude investment expenditure from the calculation of the deficit. These proposals, if carried out, could lead Italy to clash with European institutions and other member countries, who are already worried by the possible spillovers from a future mismanagement of public finances by the Italian authorities. In addition, the new coalition controversially wants to lift sanctions on Russia, which were the result of an agreement reached at European level. Further tensions may arise from migration policy. Italy is calling for a revision of the Dublin Treaty and wants to establish more stringent requirements for the reception and expulsion of immigrants. However, an agreement will be difficult to reach, given the existing divisions among EU countries.

July 08, 2018:  -Italy has asked European regulators to extend a state loan-guarantee plan that has helped its banks put a dent in Europe’s biggest pile of non-performing loans.

John Kemp from Reuters released a quality report today on the gasoline rise in America  and national travel. In the US we have seen a shift ...


John Kemp from Reuters released a quality report today on the gasoline rise in America  and national travel.

In the US we have seen a shift to larger SUV style cars due to cheaper gas - in part. When gas surges customers trade in cars and buying habits transition to more fuel efficient cars. This effects car manufacturers sales as well as inland freight costs for hauling other goods. Data suggests this could lead to inflation in the market.  - CH

“Cheap gasoline provided a significant stimulus to driving during the latter part of 2014 and throughout 2015 but the impact has faded as average pump prices have climbed back towards $3 per gallon” 


Outlook Remains Stable The economy appears to have regained some momentum in the second quarter following a weak first quarter, ...


Outlook Remains Stable

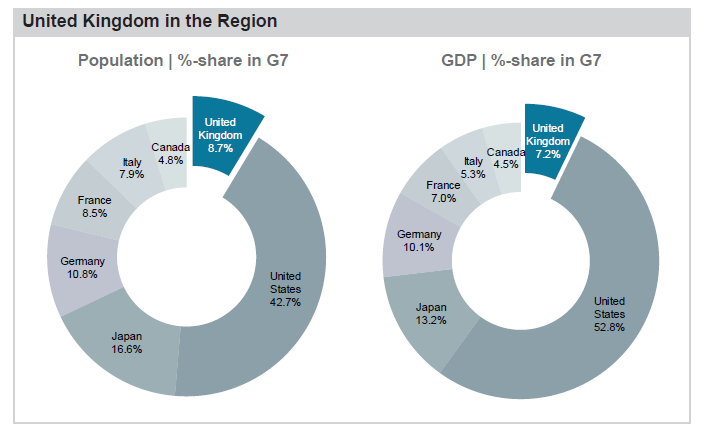
The economy appears to have regained some momentum in the second quarter following a weak first quarter, but growth is still mediocre at best. Both the manufacturing and services PMIs picked up in May, although weak new orders growth and gloomier business sentiment bode poorly for the evolution of the services PMI going forward. In addition, consumer sentiment improved in the same month, while in February–April employment continued to surge. On the downside, most new jobs were part-time, with total hours worked declining slightly. In addition, the tight labor market is still not feeding through to significantly higher pay—likely driven by weak productivity. On the political front, Brexit negotiations are making little headway on the key sticking point of the Irish border ahead of an important EU summit at the end of June. This comes against a backdrop of disagreement in parliament over MPs’ role in the Brexit process. 


Looking ahead, growth will remain muted, with fixed investment dampened by Brexit uncertainty and export growth slowing after the boost provided last year by the weaker pound. However, a slight pick-up in government spending and a loose monetary stance should support the economy. Our panelists estimate GDP growth of 1.4% in 2018, unchanged from last month’s forecast, and 1.5% in 2019.

Inflation remained at 2.4% in May, with the downward trend observed in recent months halted by higher fuel prices. Going forward, price pressures should gradually ease as the impact of the weaker pound fades, although gradually rising wage pressures and growing capacity constraints will slow inflation’s return to the Central Bank’s 2.0% target. Panelists expect inflation to average 2.5% in 2018 and 2.1% in 2019. 

The Central Bank left the base rate unchanged at 0.50% at its meeting ending on 20 June, in the face of uncertainty over the strength of the economy and gradually ebbing price pressures. However, the Bank of England (BoE) is still likely to tighten its stance later this year to ensure inflation returns to target. FocusEconomics panelists see the bank rate ending 2018 at 0.72% and 2019 at 1.03%. 

The pound has weakened against the dollar in recent weeks, on the back of the Federal Reserve’s June monetary policy tightening and ongoing Brexit uncertainty. On 22 June, the pound traded at USD 1.33 per GBP, a 1.2% weakening from the same day last month. Looking ahead, the pound is set to strengthen slightly but remain weaker than its pre-referendum levels on lingering Brexit uncertainty. Our panelists see the exchange rate ending 2018 at USD 1.39 per GBP and 2019 at USD 1.44 per GBP.


Services and manufacturing PMIs rise in May...
Pointing to pick-up in economic growth following Q1’s lull Growth in the UK services sector picked up to a three-month high in May, with the IHS Markit/CIPS UK services Purchasing Managers’ Index (PMI) rising from 52.8 in April to 54.0. May’s figure overshot market expectations of 53.0, and means the indicator moved further above the 50-point threshold that separates expansion from contraction. Despite the uptick, in May new orders grew at only a mild pace, with firms pointing to Brexit uncertainty holding back decision-making. In addition, employment growth was subdued, and businesses reported hiring difficulties; this comes amid a tight labor market, with the unemployment rate currently at a multi-decade low. Problems recruiting suitably-skilled staff generated greater wage pressures, which coupled with higher fuel bills saw input costs rise at a rapid pace. Discouragingly, business confidence waned in May, due to concerns over Brexit and consumer demand. Despite May’s improvement, Chris Williamson, Chief Business Economist at IHS Markit, cautioned that it may not last: “disappointing inflows of new work suggest that growth could wane in coming months as Brexit-related uncertainty continues to weigh on spending decisions and dampen business confidence. Measured across all major parts of the economy, new orders growth in the second quarter so far is running at the weakest since the third quarter of 2016.” The IHS Markit/CIPS manufacturing PMI increased from an over one-year low of 53.9 in April to 54.4 in May. As a result, the index moved further above the 50-point threshold that separates expansion from contraction in activity in the manufacturing sector, where it has been since August 2016. May’s rise was driven by faster growth in output. On the other hand, growth in new orders and employment eased, with the expansion in new orders dipping to the slowest in 11 months on a softer domestic market. Input price inflation rose in May on higher raw material prices and shortages, leading to an increase in output prices. Despite worsening sentiment, UK manufacturers were generally positive about production forecasts over the coming year. FocusEconomics Consensus Forecast panelists see fixed investment rising 2.3% in 2018, which is up 0.6 percentage points from last month’s forecast, and 2.0% in 2019. he Central Bank downgraded its growth forecasts in May, and now expects the economy to expand 1.4% in 2018 and 1.7% in 2019. FocusEconomics panelists expect GDP to expand 1.4% in 2018, which is unchanged from last month’s forecast, and 1.5% in 2019.


Housing market continues to lose steam in May

According to the Nationwide Building Society (NBS), house prices in the United Kingdom fell 0.2% in May compared to the previous month in seasonally adjusted terms, contrasting April’s 0.1% increase and marking the third month-on-month price decline so far this year. On an annual basis, house prices rose 2.4% in May, down from April’s 2.6% and coming in below market expectations. The average house price in May was GDP 213,618 (May 2017: GBP 208,711). May’s tepid result comes against a backdrop of sluggish economic growth and pessimistic consumer sentiment. Going forwards, house prices are likely to continue to increase at a mild rate, underpinned by tight supply. In addition, a gradual recovery in real wages could support demand. Monetary conditions will be another key determinant of the evolution of prices. Although the Bank of England kept rates constant at its June meeting, our panelists continue to expect a rate hike this year, which would have a knock-on effect on borrowing costs.


Unemployment

Employment growth remains solid but wage growth is weak The unemployment rate remained at a multi-decade low of 4.2% in the February-April period, where it has been for three consecutive rolling quarters. This was underpinned by ongoing strong employment growth: 146,000 jobs were added compared to the November-January period, once more beating market expectations. However, the rise was mainly a result of greater parttime work, with the total hours worked in the economy declining slightly. Higher employment saw the inactivity rate remain at an all-time low of 21.0%. Despite the tight labor market, the recent recovery in wages appeared to lose some impetus in February-April, with nominal earnings growth excluding bonuses dipping to 2.8% from 2.9% in the prior rolling quarter. Although real earnings continued to rise marginally, average total pay is still below the precrisis peak reached in 2008. The Central Bank expects nominal regular pay growth to continue to hover slightly below 3.0% this year. As inflation gradually declines, this should see a gradual uptick in real wage growth, although it will likely remain sluggish. Public-sector pay—which has been constrained in recent years by austerity measures—is likely pick up as the government gradually lifts its spending straightjacket thanks to an improved fiscal situation. FocusEconomics Consensus Forecast panelists expect unemployment to average 4.3% in 2018, which is down 0.1 percentage points from last month’s forecast, and 4.5% in 2019.


Thank you Focus Economics for the economic reporting. Please visit Focus here. 
Economic growth appears on track to record a stellar performance in Q2, fueled by strong business investment, tax cuts and an ever-t...


Economic growth appears on track to record a stellar performance in Q2, fueled by strong business investment, tax cuts and an ever-tightening labor market boosting consumer spending. In May, the unemployment rate hit a new low, and growth in retail sales accelerated as consumer confidence remained near a historic high. Furthermore, housing starts picked up in the same month, helped by rising wages and lower taxes boosting household incomes. Survey data for May indicates the private sector has so far been unfazed by current tensions with trade partners, although President Trump’s rapidly escalating rhetoric vis-à-vis China in past weeks could prove damaging to business confidence. The month ahead might represent a critical junction, as new restrictions on investments between Chinese and American firms are set to be unveiled on 30 June, while reciprocal tariffs with China and retaliatory measures from Canada will take effect in early July. 


The exceptional domestic momentum has so far been unmarred by signs of moderating growth in key trading partners. Although recent tariff measures will likely have minimal impact, the increasingly likely escalation of the dispute with China into a trade war is a major downside risk, which could weigh on business sentiment and investment. Faster monetary policy tightening and high fiscal deficits should further dampen growth in the medium-term. FocusEconomics panelists see GDP expanding 2.8% in 2018, unchanged from last month’s estimate. 

In 2019, growth is seen moderating to 2.4%. Inflation hit a 5-year high of 2.8% in May, up from 2.5% in April. The 12–13 June FOMC meeting communiqué suggests the Fed is satisfied with the current underlying inflation trend and might tolerate inflation overshooting its target for a limited period. Inflation is likely to remain strong in the near term thanks to buoyant growth, before moderating next year. Our panel sees inflation averaging 2.5% in 2018 and 2.2% in 2019. 

The Federal Reserve raised the federal funds rate by 25 basis points to 1.75%–2.00% at its 12-13 June FOMC meeting. It also raised its median projection from three hikes to four in 2018, meaning two more rate increases are now the baseline scenario for this year. This assessment is shared by our panel, which expects the federal funds rate to end 2018 at 2.44% and 2019 at 3.06%. An increasing interest rate differential coupled with strong economic data pushed the dollar higher against main trading partners’ currencies in June. On 22 June, the dollar index traded at 94.5, a month-on-month strengthening of 1.0%.

Decent read here on how the lack of union membership has allowed for greater wage inequality. My argument is that we are more deal...


Decent read here on how the lack of union membership has allowed for greater wage inequality. My argument is that we are more dealing with a third and fourth industrial revolution, coupled with subsequent labor issues, on a system which greatly rewarded the entrepreneur and capitalistic class. Payroll and wages are - by design - capped at levels. The largest offenders are the largest employers.
 - CH

“The labor market and economy are evolving in a way that’s giving employers increased power over workers,” he said. “Unions were, at least at one point, an important institution for resisting and adding some balance.”

Sales of new single-family houses in May 2018 were at a seasonally adjusted annual rate of 689,000, according to estimates released j...


Sales of new single-family houses in May 2018 were at a seasonally adjusted annual rate of 689,000, according to estimates released jointly today by the U.S. Census Bureau and the Department of Housing and Urban Development. This is 6.7 percent (±14.1 percent)* above the revised April rate of 646,000 and is 14.1 percent (±19.9 percent)* above the May 2017 estimate of 604,000. Sales Price The median sales price of new houses sold in May 2018 was $313,000. The average sales price was $368,500. For Sale Inventory and Months’ Supply The seasonally-adjusted estimate of new houses for sale at the end of May was 299,000. This represents a supply of 5.2 months at the current sales rate.

Housing in America is going full blast. All across the spectrum there is activity and it seems to be increasing despite recent rate...


Housing in America is going full blast. All across the spectrum there is activity and it seems to be increasing despite recent rate hikes. The independent builder is starting to creep out into the spectrum and speculators are taking on more risk. - CH

Privately-owned housing starts in May were at a seasonally adjusted annual rate of 1,350,000. This is 20.3 percent (±14.4 percent) above the May 2017 rate of 1,122,000...

https://www.census.gov/construction/nrc/pdf/newresconst.pdf

REAL SECTOR | Growth momentum stays solid in most countries, although Puerto Rico distorts the regional picture Preliminary estimate...


REAL SECTOR | Growth momentum stays solid in most countries, although Puerto Rico distorts the regional picture Preliminary estimates suggest the economy of Central America and the Caribbean remained largely in good shape at the outset of the year, with growth expected to have reached 2.1% annually in Q1. This marks a 0.6 percentage-point downward revision compared to last month’s estimate, largely driven by a larger expected contraction in Puerto Rico, one of the region’s largest economies in nominal GDP terms. However, excluding Puerto Rico, the region’s Q1 growth figure would have seen only a mild downward revision compared to last month’s forecast. The Dominican Republic has been the region’s standout performer so far this year, with the economy buoyed by monetary stimulus that has spurred credit growth. Following a stellar Q1 GDP reading, economic activity increased at an over one-year high in April, spearheaded by the construction sector. New hotel, residential housing and energy projects currently underway are turbocharging activity in the sector, as firms take advantage of cheaper financing conditions. While national accounts figures for the first quarter are still outstanding in Guatemala, economic activity growth also edged higher in the first four months of the year compared to Q4. The picture is similar in Costa Rica: Economic activity growth in the January–April period tracked slightly higher than in October– December. Costa Rica’s fiscal situation is still worrying but has improved slightly in recent weeks, after the new government announced austerity measures to rein in the public wage bill. However, more fundamental reforms are still needed to put public finances on a sustainable long-term footing. On the other hand, the Panamanian economy has lost steam in recent months on the back of a downturn in the construction sector, which was deepened by a month-long strike paralyzing building activity in the country. To reignite growth, the government recently announced a substantial spending boost for large-scale infrastructure projects. Honduras has also seen momentum ebb so far this year due to a weaker agricultural sector, partly caused by unusually warm weather. Throughout the region, countries have seen a continuing surge in remittances so far this year, linked to a robust labor market in the U.S, where the unemployment rate is currently at the lowest level in 18 years. In May, Guatemala saw the highest inflow of 1.5 2.0 2.5 3.0 3.5 4.0 Q1 15 Q1 16 Q1 17 Q1 18 Q1 19 2.0 2.4 2.8 3.2 3.6 4.0 Nov Feb May Aug Nov Feb May 2018 2019 Central America & Caribbean Economic Growth Change in GDP forecasts Note: GDP, real annual variation in %, Q1 2015 - Q4 2019. Note: GDP, evolution of 2018 and 2019 forecasts during the last 18 months. FOCUSECONOMICS Summary FocusEconomics Consensus Forecast Central America and Caribbean | 4 June 2018 remittances on record at over USD 800 million. This influx of capital is supporting domestic wages, private consumption and international reserves. In contrast, the regional external sector’s contribution to growth has likely weakened so far this year on a higher oil import bill. On the political scene, ongoing unrest in Nicaragua is generating uncertainty and damaging the country’s relatively successful economic trajectory over recent years. Tourism and inward investment will almost certainly be hard by the upheaval—as the Central Bank’s governor recently warned—as will domestic sectors. Efforts are underway to reestablish a dialogue, which broke down in May, between the government and different sectors of civil society. Talks have yet to begin, however, and in the meantime violence continues. OUTLOOK | Regional growth revised down on worsening dynamics in Puerto Rico The Puerto Rican economy is expected to drag heavily on regional growth this year, as the economy continues to suffer the aftereffects of hurricanes Maria and Irma, and the ensuing destruction to physical infrastructure and power outages. Elsewhere in the region, the outlook is somewhat brighter. Economies will continue to benefit from fiscal stimulus in the U.S—by far Central America and the Caribbean’s largest trading partner—which should in turn continue to boost remittances, exports and tourist arrivals. However, higher international oil prices will weigh on the region’s external sector. Key downside risks stem from the potential faster- than-expected monetary tightening by the U.S. Federal Reserve— which would weigh on regional credit growth, investment and private spending—and tougher U.S. immigration policy, which could disrupt remittance inflows. Citizens from El Salvador, Haiti, Honduras and Nicaragua currently residing in the U.S. are already set to see their Temporary Protected Status end within a few years, which could lock many of them out of the U.S. labor market. FocusEconomics panelists expect regional GDP growth of 2.1% this year, which is down 0.5 percentage points from last month’s estimate. This is largely driven by a greater expected contraction in regional heavyweight Puerto Rico, as the full impact of the devastation caused by last year’s hurricanes becomes clear. There was also a notable downgrade for Nicaragua due to continuing violent unrest. Belize, Haiti, Panama and Trinidad and Tobago also saw their projections downgraded this month. Conversely, the GDP forecast for the Dominican Republic was revised upwards following the recent string of positive economy data, as was Jamaica’s. The region’s remaining economies saw their projections unchanged. Regional GDP growth is seen accelerating to 3.7% in 2019. Panama’s economy is expected to log the highest increase in the region despite a soft start to the year, the result of higher Panama Canal earnings and robust fixed investment levels. GDP in Panama is projected to increase 5.4%. Conversely, Puerto Rico is expected to be the region’s worst performer, recording a contraction of 8.0% in FY 2018.


- For a sample report from FocusEconomics

- For A Free Trial From FocusEconomics

- Ask FocusEconomics For A Custom Report


From The BLS : Over the last 12 months, food prices increased 1.2 percent, with prices for food away from home rising 2.7 percent, an...


From The BLS:

Over the last 12 months, food prices increased 1.2 percent, with prices for food away from home rising 2.7 percent, and prices for food at home rising 0.1 percent. Prices for meats, poultry, fish, and eggs increased 2.3 percent over the last year; that was the only one of the six major grocery store food groups to increase.
Energy prices increased 11.7 percent over the past year, with prices for three of the four major components rising. Gasoline prices increased 21.8 percent, fuel oil prices rose 25.3 percent, and electricity prices increased 1.0 percent. Prices for natural gas fell 0.8 percent over the year.
Prices for all items less food and energy rose 2.2 percent over the past 12 months. Prices for shelter rose 3.5 percent over the last 12 months, and prices for medical care services rose 2.3 percent. Prices that declined over the past 12 months include those for new vehicles, airline fares, used cars and trucks, and communication.


The Consumer Price Index for All Urban Consumers (CPI-U) increased 0.2 percent in May on a seasonally adjusted basis after rising 0.2 percent in April, the U.S. Bureau of Labor Statistics reported today. Over the last 12 months, the all items index rose 2.8 percent before seasonal adjustment. The indexes for gasoline and shelter were the largest factors in the seasonally adjusted increase in the all items index, as they were in April. The gasoline index increased 1.7 percent, more than offsetting declines in some of the other energy component indexes and led to a 0.9-percent rise in the energy index. The medical care index rose 0.2 percent. The food index was unchanged over the month. The index for all items less food and energy rose 0.2 percent in May. The shelter index rose 0.3 percent in May. The indexes for new vehicles, education and communication, and tobacco increased in May, while the indexes for household furnishing and operations, and used cars and trucks fell. The indexes for apparel, recreation, and personal care were unchanged. The all items index rose 2.8 percent for the 12 months ending May, continuing its upward trend since the beginning of the year. The index for all items less food and energy rose 2.2 percent for the 12 months ending May. The food index increased 1.2 percent, and the energy index rose 11.7 percent.

Atlanta Fed president and CEO Raphael Bostic speaks at the Rotary Club of Savannah about the Fed's recent policy move and economic resil...


Atlanta Fed president and CEO Raphael Bostic speaks at the Rotary Club of Savannah about the Fed's recent policy move and economic resilience:
  • Bostic sees output growing at a moderately above-trend pace this year and next, then slowing to a pace that corresponds with the longer-run potential of the economy, which is slightly less than 2 percent.
  • Bostic believes that community-based investment is one way to think about the kinds of local investments that help to translate growth into community assets that expand opportunity for people living in conditions of economic distress.

Copyright 2008 - 2025

(C) Atlantic Playbook / ZMI